Got a cheque from a customer and not sure whether it can be discounted? It’s one of the most common questions we get. The answer depends on the type of cheque, its due date and the transaction behind it. In this article we go through three types of cheques businesses receive: current cheques, post-dated cheques and “account payee only” cheques. We explain what each one means for discounting and what to check before you send it to us.
Current cheque
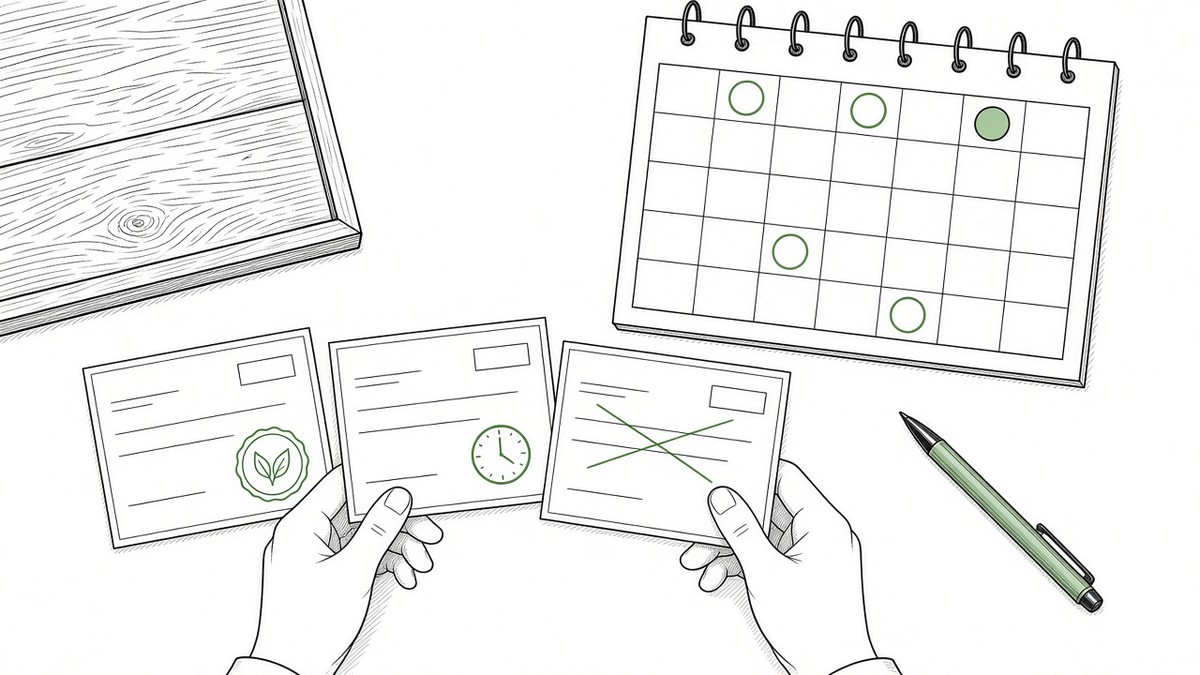
A current cheque is one dated today or on a date that has already passed. In theory you could simply deposit it and wait, but sometimes a business needs the money now – for example, to pay a supplier or close an order. You can bring current cheques to us for review too. If the cheque is approved, you get the money at the time of the transaction.
Post-dated cheque
A post-dated cheque is one whose date hasn’t arrived yet. Many businesses receive cheques like these from customers who pay on shotef plus terms (end of the month plus a set number of days), and the money only comes in on the date written on the cheque. This is where post-dated cheque discounting can help: instead of waiting, you can ask to receive the money before the due date.
We review post-dated cheques up to 120 days for discounting. As long as your cheque falls within that range, you can send it for review. Every cheque is reviewed on its own merits.
“Account payee only” cheque
A cheque marked “account payee only” (in Hebrew, lamutav bilvad) is meant only for the person or business named on it. So when a cheque like this is made out to your business alone, we can’t discount it as it stands. There’s a simple solution:
Got an “account payee only” cheque? Ask the person who wrote the cheque to put both names on it: “Pay to the order of [your name] or Y.D Amigo Ltd” (in Hebrew on the cheque: «לפקודת [your name] או י.ד אמיגו בע״מ»), and we’ll check it for discounting.
If you know in advance that you’ll want to discount a particular cheque, ask for this wording when the customer writes it. It saves you having to go back to them later.
What do we check on every cheque?
The review focuses mainly on who wrote the cheque and the quality of the transaction, not only on your financial history. Subject to review and approval.
In other words, we look at who wrote the cheque and at the transaction it was given for: what was paid for, between whom, and whether the details on the cheque match. Every cheque is reviewed, even when it looks perfectly fine, and the decision is made for each cheque on its own merits.
Before you send a photo: a short checklist
To keep the review free of delays, check a few things before you take the photo:
- The details are legible: the writer’s name, the cheque number, the amount and the date are clearly visible in the photo.
- The amounts match: the amount in figures is the same as the amount in words.
- It’s signed: the cheque is signed by the person who wrote it.
- The name is right: the name on the cheque is the exact name of your business. If it’s an “account payee only” cheque, see the explanation above.
- The date is in range: the cheque is current or post-dated up to 120 days.
Cheques that need a closer look
In some situations it’s worth giving us a few extra details when you send the photo, so the review can be more accurate:
- Crossings-out or corrections: if the amount, date or name on the cheque has been corrected, tell us. You may need to ask the writer for a new cheque.
- Several cheques from the same customer: if you’ve received a series of post-dated cheques from the same customer, send them all together so we can see the full picture.
The more you tell us about the transaction up front, the easier it is to give you a clear answer.
How do you get the money?
Once the cheque is approved, you’re paid at the time of the transaction – in cash, by bank transfer or on a prepaid card, according to the rules below. There’s no minimum and no maximum amount.
A cheque of up to ₪6,000 (inclusive) can be paid out in full in cash, with no need for an invoice, receipt or allocation number. The exemption covers the transaction documents only, not identification: for every transaction you need an Israeli ID card (teudat zehut) or a passport. For transactions over ₪50,000, also bring a second ID document: a passport or a driver’s licence.
For businesses, a cheque over ₪6,000 and up to ₪25,000 inclusive can be paid out in full in cash against an invoice, a receipt and an allocation number (the number the Israel Tax Authority assigns to the invoice). For a cheque over ₪25,000, you can receive in cash the lower of 10% of the cheque amount or ₪6,000, against the same documents. For a cheque over ₪6,000, cash cannot be paid without these documents.
Got several cheques? If each cheque is up to ₪25,000 (inclusive) and each has its own invoice and allocation number, plus a receipt as required, all of them can be paid out in cash, even if they’re from the same writer. When several cheques relate to the same invoice or allocation number, the cash limit is checked against their total.
Anything above the permitted cash amount can be paid by bank transfer and/or on a prepaid credit card, up to ₪10,000 on the card. You can split it: up to ₪10,000 on a prepaid card and the rest by bank transfer.
We’ve been operating for 17 years, with more than 4,000 customers, from our branch at Levinsky 52, Tel Aviv. All the details about the service are on our cheque discounting for businesses page.
Not sure whether your cheque qualifies? Send a photo of the cheque on WhatsApp and we’ll check it. You can also reach us through our contact page.
Frequently asked questions
Can a current cheque be discounted?
Yes. You can bring current cheques and post-dated cheques up to 120 days for review. Every cheque is reviewed on its own merits.
How far ahead can a post-dated cheque be dated?
We review post-dated cheques up to 120 days for discounting.
What do I do with an “account payee only” cheque?
Ask the person who wrote the cheque to put both names on it: “Pay to the order of [your name] or Y.D Amigo Ltd”, and we’ll check it for discounting.
Does the review depend on my financial history?
The review focuses mainly on who wrote the cheque and the quality of the transaction, not only on your financial history.
Nothing stated above is a commitment to provide credit. Final credit terms are set according to the specific terms of each customer’s transaction. Failure to repay the loan or the credit may result in late-payment interest and enforcement proceedings (Execution Office).
Credit provider licence – basic, No. 63112